Build-and-transfer quantitative consulting
XuSinger helps credit, finance, insurance, and research teams turn technical ambiguity into working models, workflows, documentation, and training. We build for the client's environment, transfer the code and methods, and remain available for support, monitoring, or future builds.
Client-owned deliverables. Practical production handoff. No proprietary platform lock-in.
Core services
-
Default, pricing, underwriting, monitoring, and portfolio models.
Scorecards, ML models, segmentation, feature engineering, and explainability support.
Model reports, validation-ready documentation, governance and monitoring design.
Independent external second line model validation, including full first line review and model validation report documentation.
Python, SAS, R, SQL/Snowflake workflows.
-
Production scoring runners, batch pipelines, decision-engine handoff, and QA checks.
Regression tests, UAT scripts, release notes, reproducible runs, and audit trails.
Conversion of notebooks, spreadsheets, and prototypes into maintained workflows.
Support without forcing clients into a subscription platform.
-
Balance sheet, P&L, cash-flow, projection, and scenario models.
Driver-based forecasting, allocation/scheduling optimization, and reporting automation.
Spreadsheet cleanup, workflow streamlining, data ingestion, and controls.
Designed for business use, documentation, and future internal ownership.
-
Pricing, fraud/anomaly analytics, portfolio monitoring, and risk reporting.
Actuarial models, experience studies, lapse, mortality, utilization, and scenario analysis.
ALM/ERM, Monte Carlo simulation, capital/risk analytics, and executive reporting.
Translation between quantitative teams, business owners, and technology teams.
-
Custom training in actuarial science, data science, and practical ML.
Workshops in Python/SQL, model lifecycle, deployment, monitoring, and documentation.
Project-based exercises, code notebooks, assessments, and reusable internal playbooks.
Built for teams that need adoption, not just delivery.
Two partners combining quantitative finance, actuarial science, software delivery, and biostatistical research methods.
Best fit: teams that need rigorous modelling and practical handoff, but do not want vendor lock-in or a black-box platform.
Partner profiles
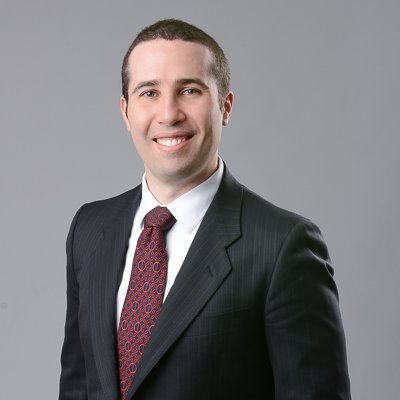
Basil Singer, PhD, FSA, CERA
Credit risk | Quant engineering | Actuarial modelling
- Actuarial data scientist and quant engineer with PhD-level statistics, FSA/CERA credentials, and credit-risk model experience.
- Founder/principal consultant for Canadian and U.S. clients across credit risk, financial modelling, scheduling, forecasting, automation, and analytics.
- Built credit-risk models and analytics using Python, SAS, R, Snowflake, and custom libraries; built automation and regression-testing tools.
- Enterprise banking data science experience across commercial analytics, capital-markets pricing, NLP, fuzzy matching, knowledge graphs, and anomaly detection.
- University of Toronto teaching in graduate data analytics and actuarial science, including model lifecycle, deployment, monitoring, Python/SQL, and life contingencies.
Tools / methods: Python, SQL, C#, R
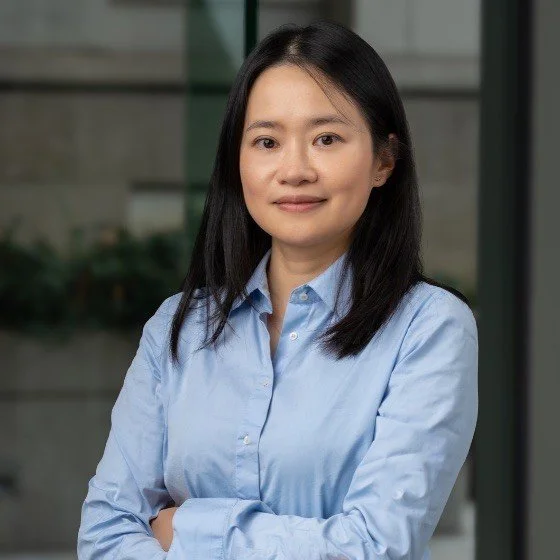
Changchang Xu, PhD
Biostatistics | Cancer research | Survey methods
- Biostatistician specializing in survival analysis, longitudinal data, missing data methods, experimental design and survey sample analysis, with working experience in clinical data, electronic health record data and credit risk data.
- Research depth in mixture cure survival models, multiple imputation, penalized likelihood, and sparse/low-event datasets.
- Published work motivated by breast cancer prognosis and interventions studies for primary care in diabetes with longitudinal hierarchical data.
Tools / methods: R, SAS, Python, PowerBI, Snowflake, PLINK, Git
Begin Your Consultation
Submit the inquiry form to initiate a confidential discussion and explore how these solutions can advance your strategic priorities.